Legal
Fideicomiso Explained: How the Mexican Bank Trust Works for Foreign Buyers
What a fideicomiso is, why foreigners need one on the Mexican coast, how much it costs, how long it lasts and what rights it gives you, explained in plain English.
 By Pierre, founder of HolaMaya · November 2, 2026 · 3 min read
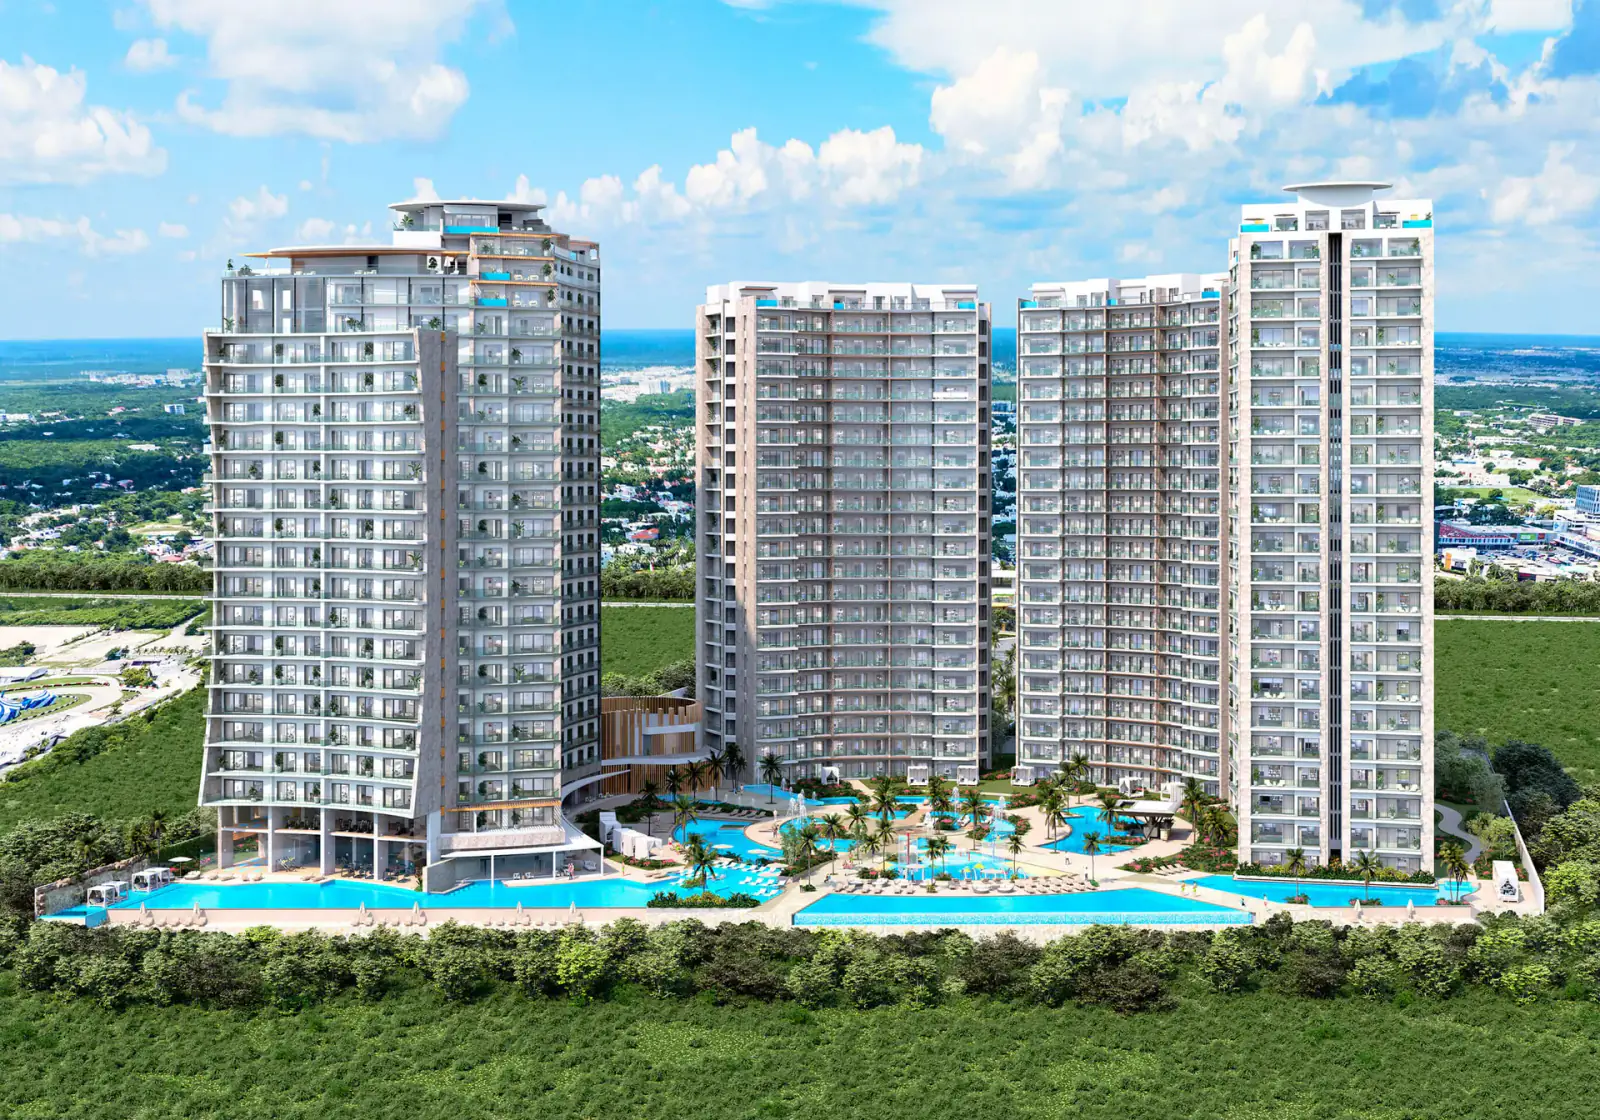
If you buy a home in Playa del Carmen, Tulum or Cancún as a foreigner, you will almost certainly hold it through a fideicomiso. The word sounds intimidating, but the structure is simple and has been used by foreign buyers for decades.
What is a fideicomiso?
A fideicomiso is a bank trust. A Mexican bank (the fiduciario, or trustee) holds the legal title to the property, and you are the beneficiary (fideicomisario). The bank is not the owner in any practical sense: it must follow your instructions and cannot sell, rent or mortgage the property without them.
As beneficiary you can:
- Live in, use and enjoy the property.
- Rent it out, short or long term (subject to the building's rules).
- Sell it, or transfer your rights to a buyer.
- Mortgage it.
- Name substitute beneficiaries who inherit it, often without going through Mexican probate.
Why is it required?
Mexico's Constitution restricts direct foreign ownership of land within 50 km of the coast and 100 km of the borders. The fideicomiso was created to let foreigners buy residential property in these areas with full economic rights. The entire Riviera Maya is inside this restricted zone.
How long does it last?
A residential fideicomiso has a term of 50 years and can be renewed. When you sell, the buyer can take over your trust or set up a new one, so the term restarts.
How much does it cost?
Expect two types of cost:
- Set-up: the bank's opening fee, the permit from the Ministry of Foreign Affairs (SRE) and the notary's work. These are part of your closing costs.
- Annual fee: banks charge a yearly administration fee, commonly in the range of several hundred to around a thousand US dollars depending on the bank and the property.
Compare banks before closing. Fees, service and responsiveness vary, and you will deal with the bank again when you sell or update beneficiaries.
Fideicomiso or Mexican corporation?
| Fideicomiso | Mexican corporation | |
|---|---|---|
| Best for | Homes, holiday homes, rentals | Commercial property, development |
| Who holds title | Mexican bank as trustee | The company directly |
| Ongoing obligations | Annual bank fee | Accounting, tax filings, legal representative |
| Inheritance | Substitute beneficiaries | Company shares |
For a residential purchase, the fideicomiso is usually simpler and cheaper. A corporation makes sense for commercial activity, and your accountant should confirm the tax treatment.
Is it safe?
Yes. The trust is regulated by Mexican banking law, the bank acts on your instructions, and the property is not part of the bank's assets: if the bank had financial problems, your trust would be transferred to another institution. The real risks in Mexican real estate lie elsewhere: unclear title, unpaid debts or unpermitted construction. That is why proper due diligence matters more than the trust itself.
Buying a pre-sale unit with a fideicomiso
With pre-sale (preventa) condos, you usually sign a purchase agreement with the developer during construction, and the fideicomiso and deed are completed at delivery. Some developments use a master trust from the start. Ask how your payments are protected until the deed is signed.
General information only, not legal advice. Your notary will confirm the structure and costs for your purchase.
Looking for a home? See our houses and villas for sale and Cancún real estate.